
Fourth place, one point from history: what the GFCI actually measures
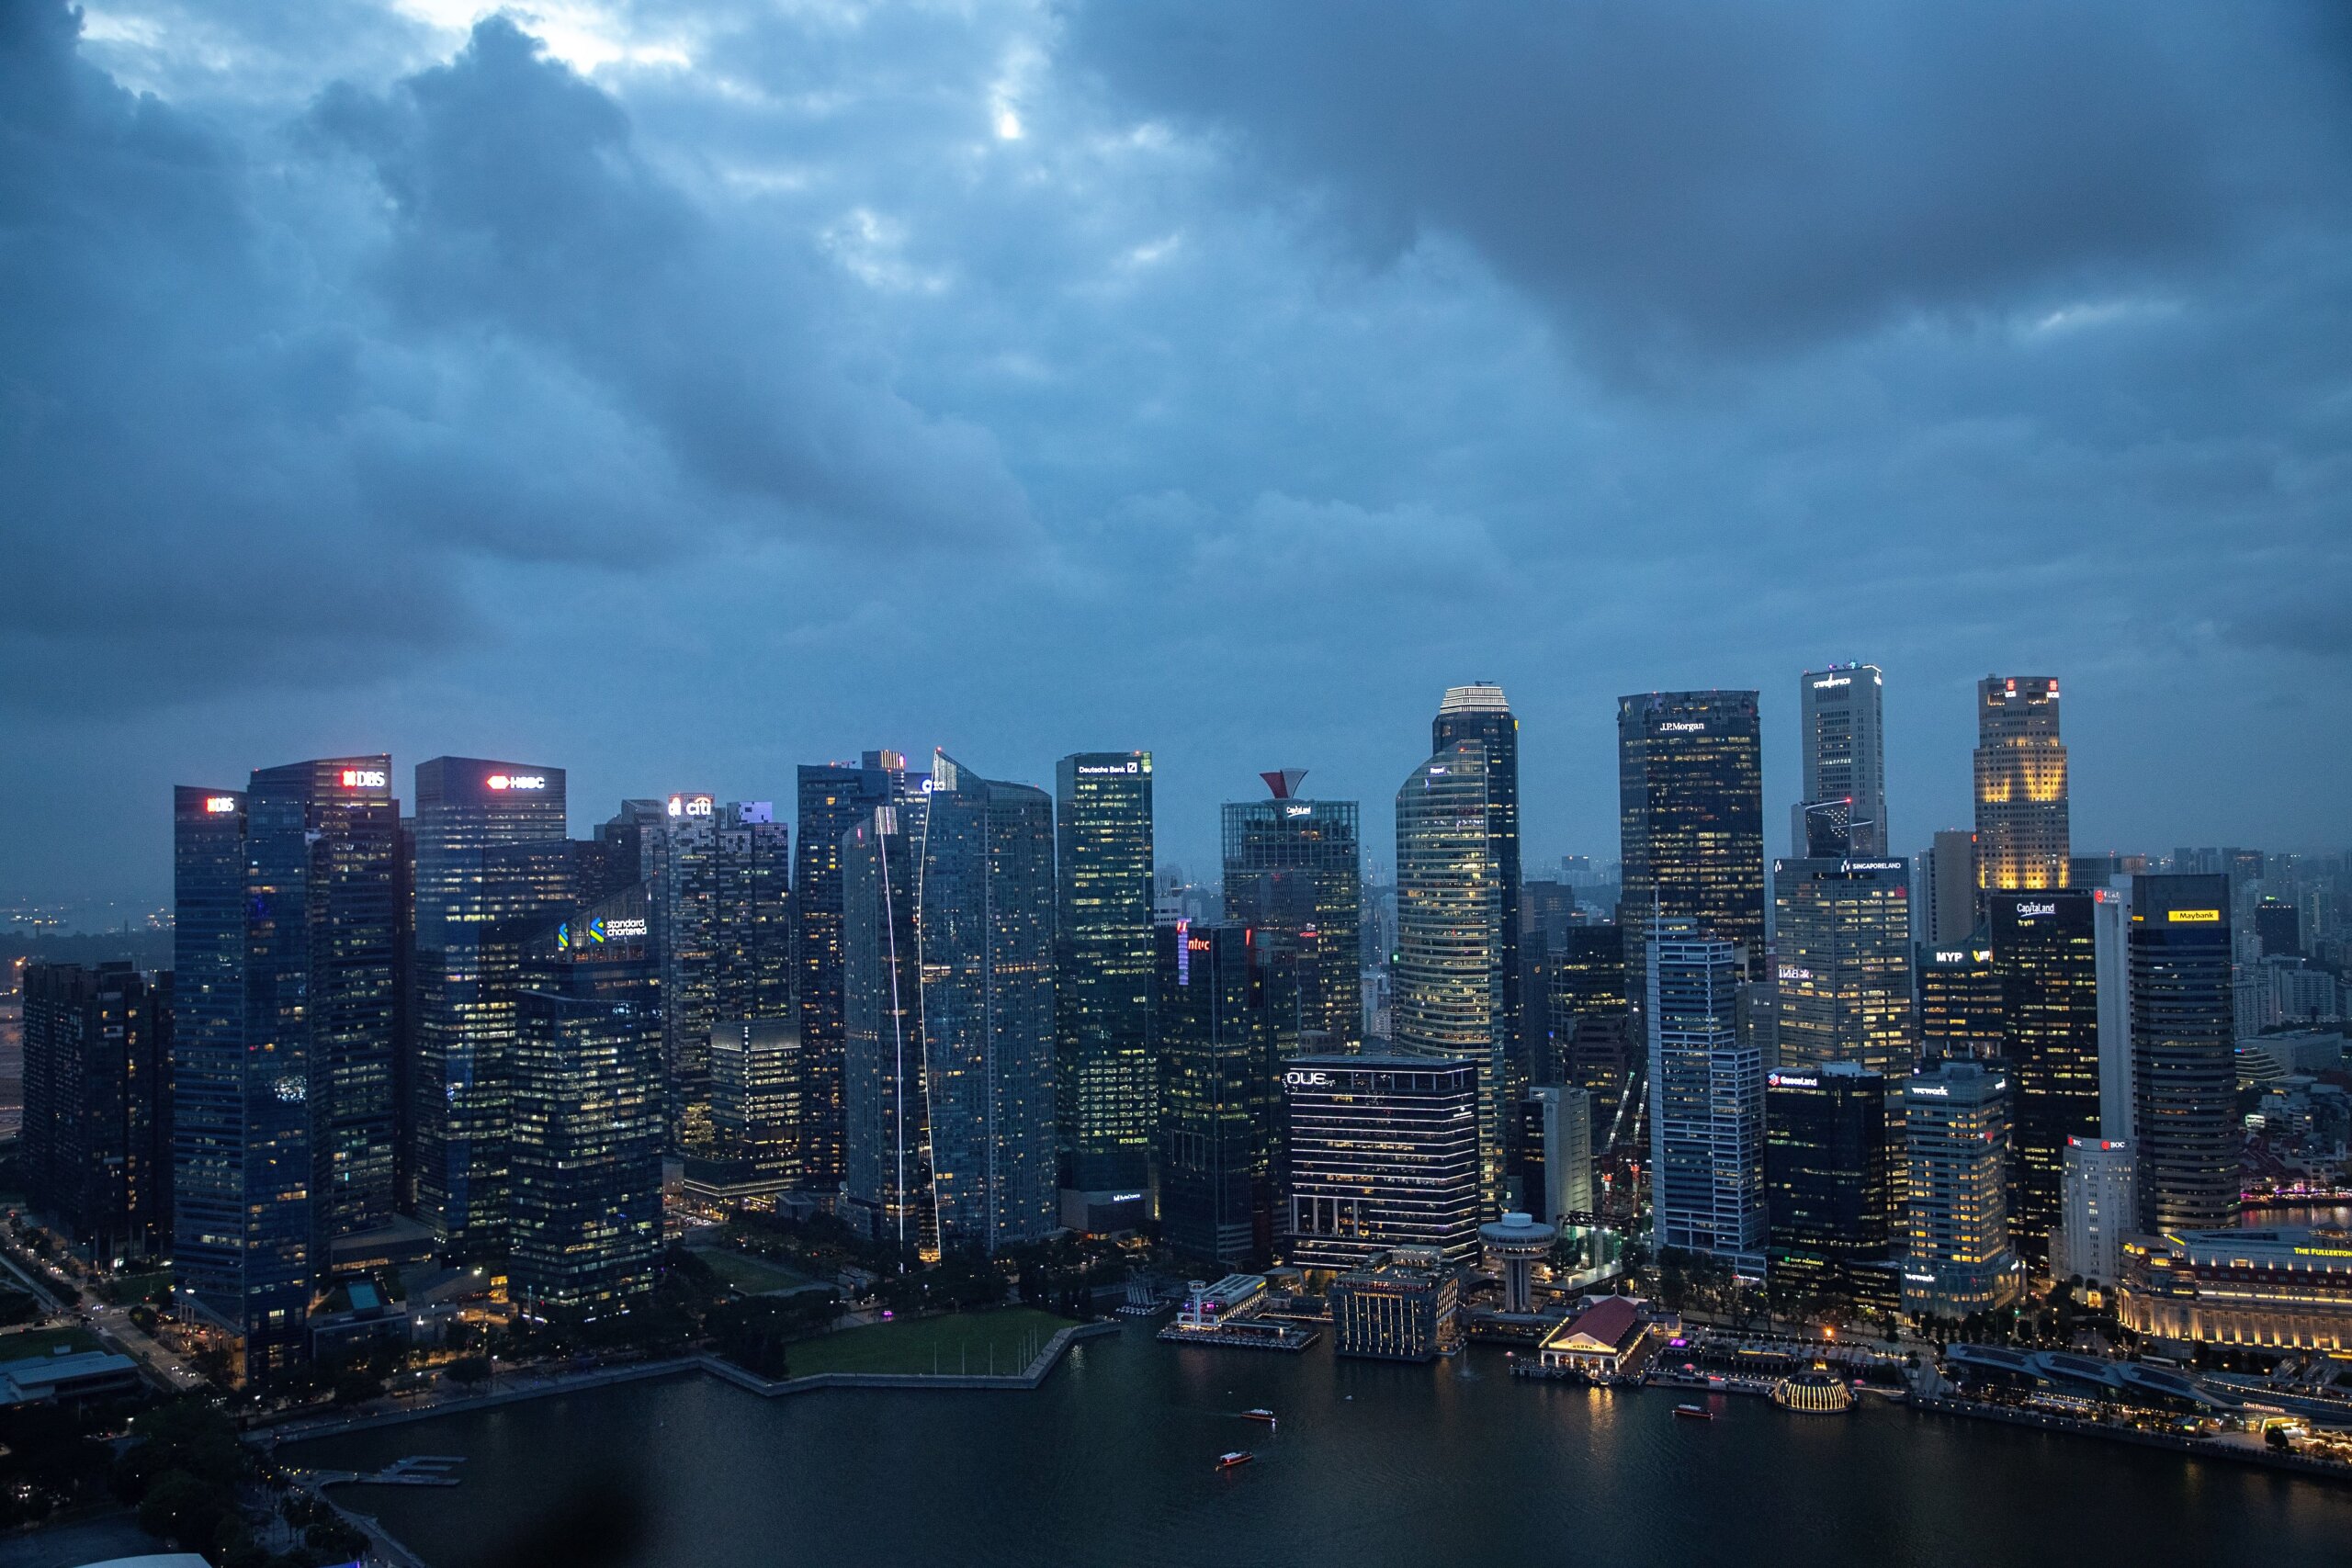
New York holds the top spot in the Global Financial Centres Index at 767. Singapore sits fourth, at 764. Three points separate the world’s top four financial centres, and one point separates Singapore from third place. Before treating that gap as meaningful, it’s worth understanding exactly what the index is measuring — and what it isn’t.
The scoreboard, precisely
GFCI 39, published on 26 March 2026 by Z/Yen and the China Development Institute, put New York first with a rating of 767, London second at 766, Hong Kong third at 765, and Singapore fourth at 764. Three points cover the entire top four. San Francisco, in fifth, trails at 744 — a twenty-point gap that dwarfs anything separating the leaders. The report’s own framing is blunt about what this means: the top four are, functionally, in a photo finish, while everyone below them is racing for a distant fifth.
Six months earlier, in the September 2025 edition, Singapore had actually gained 13 points and sat exactly where it does now — one point behind Hong Kong. The ranking order hasn’t shifted; the closeness has simply persisted across two consecutive editions.
What the index is actually built from
The GFCI isn’t a single metric — it’s a composite of 147 “instrumental factors,” quantitative data points sourced from third parties including the World Bank, the OECD and the United Nations, covering things like business environment, infrastructure, human capital and regulation. Onto that quantitative base, Z/Yen layers survey responses: GFCI 39 drew on 34,468 individual assessments from 5,218 respondents working across the global financial industry, each rating the centres they have direct experience with. This hybrid structure matters more than most coverage of the index acknowledges. Half the ranking rests on hard data that changes slowly — infrastructure doesn’t move much in six months. The other half rests on how financial professionals currently feel about a city, which can shift with a single high-profile regulatory announcement, a prominent relocation, or simply a few months of favourable headlines. A one-point gap sitting inside a system this sensitive to sentiment is not the same thing as a one-point gap in, say, GDP.
Where Singapore actually leads — and where it doesn’t
The aggregate score obscures a more useful picture. GFCI 39 also breaks its ranking down by industry sector, and here Singapore doesn’t merely compete with Hong Kong — it beats it outright in two categories, taking the leading position where New York and Hong Kong each top three sectors apiece. Singapore also outranks London specifically in FinTech, sitting fourth globally on that measure, just ahead of London in fifth, even as Hong Kong holds the top FinTech spot overall.
Hong Kong’s government, in its own response to GFCI 39, emphasised regulatory predictability, its Asia-Pacific lead, and first-place global fintech offerings score — a reminder that both cities are actively managing how this index is read domestically, not passively receiving a verdict. The report’s respondents were also asked what matters most in regulation specifically: predictability ranked first, followed by speed of response and flexibility, with cost rated the least important factor of all. For a jurisdiction decision, that ordering is arguably more useful than the headline rank itself — it tells you what the market’s own practitioners are actually optimising for.
Why a one-point gap shouldn’t decide anything
The GFCI’s authors describe the top four as effectively tied, and the data supports that description more than a decisive four-way ranking would. Reading a one-point movement as a meaningful shift in fundamentals is over-interpreting a figure built substantially from six months of sentiment among a self-selected pool of survey respondents. The same index has shown Hong Kong and Singapore trade the third and fourth spots back and forth across recent editions without either city’s underlying business environment changing in any way a company or family office would actually notice. What the index is genuinely useful for is trend-spotting at the regional level, not adjudicating between two specific, closely matched cities on any given day. Six of the top ten centres in GFCI 39 are now in Asia-Pacific — Hong Kong, Singapore, Shanghai, Seoul, Shenzhen and Tokyo — a structural shift in where financial activity concentrates that matters far more than whether Singapore sits third or fourth in any single edition.
What this means for an actual jurisdiction decision
For a family office or fund principal weighing where to base operations, the GFCI functions best as a sanity check, not a deciding input. Singapore and Hong Kong increasingly serve different roles within a regional capital strategy rather than competing head-to-head for the identical mandate — Hong Kong’s proximity to mainland China and its fintech infrastructure serve a different purpose than Singapore’s stability, tax treaties and family office ecosystem. The real due diligence lives in specifics the GFCI doesn’t fully capture: bilateral tax treaties, talent availability, regulatory responsiveness on a specific licence application, and how a jurisdiction has actually behaved during the periods that test it.
A one-point gap in a 767-point index, moving within a band that both cities have occupied interchangeably for a year, is not a signal to act on. It’s a snapshot of sentiment among 5,218 people, taken on one day in March. Treated as anything more than that, it tells an investor considerably less than the sector-by-sector breakdown sitting one page further into the same report.