
From 400 to 2,000: the anatomy of Singapore’s family office boom
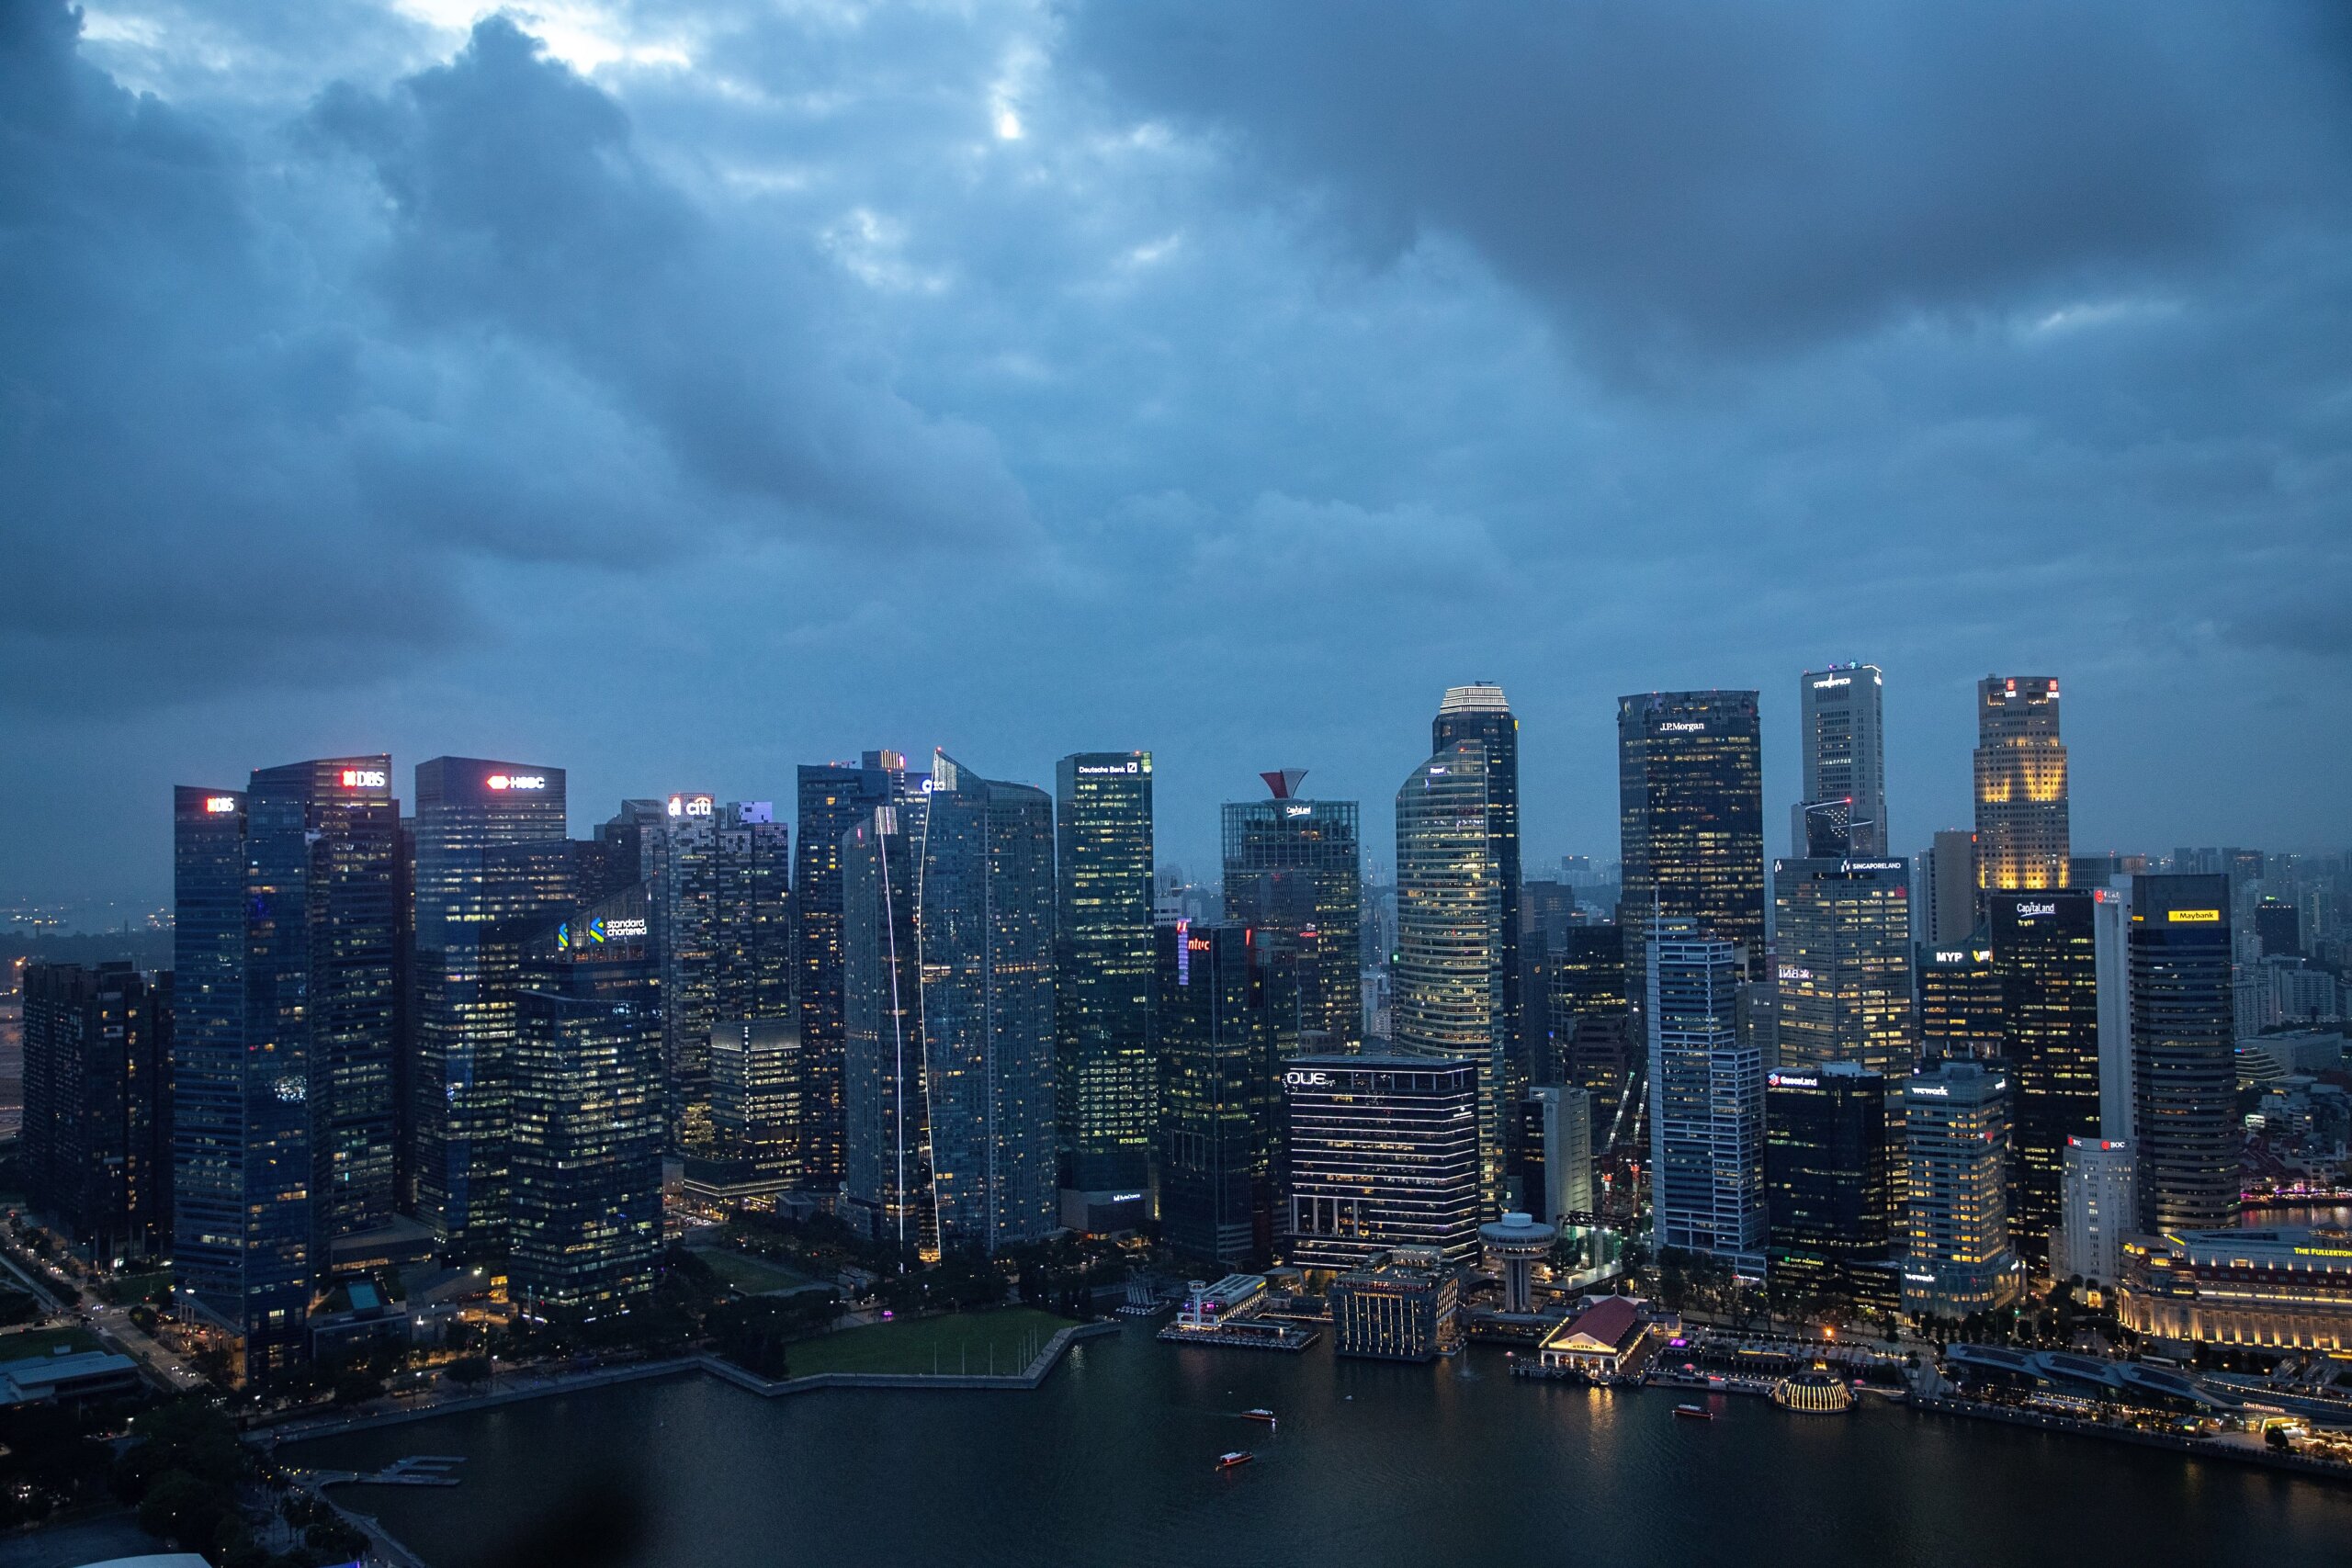
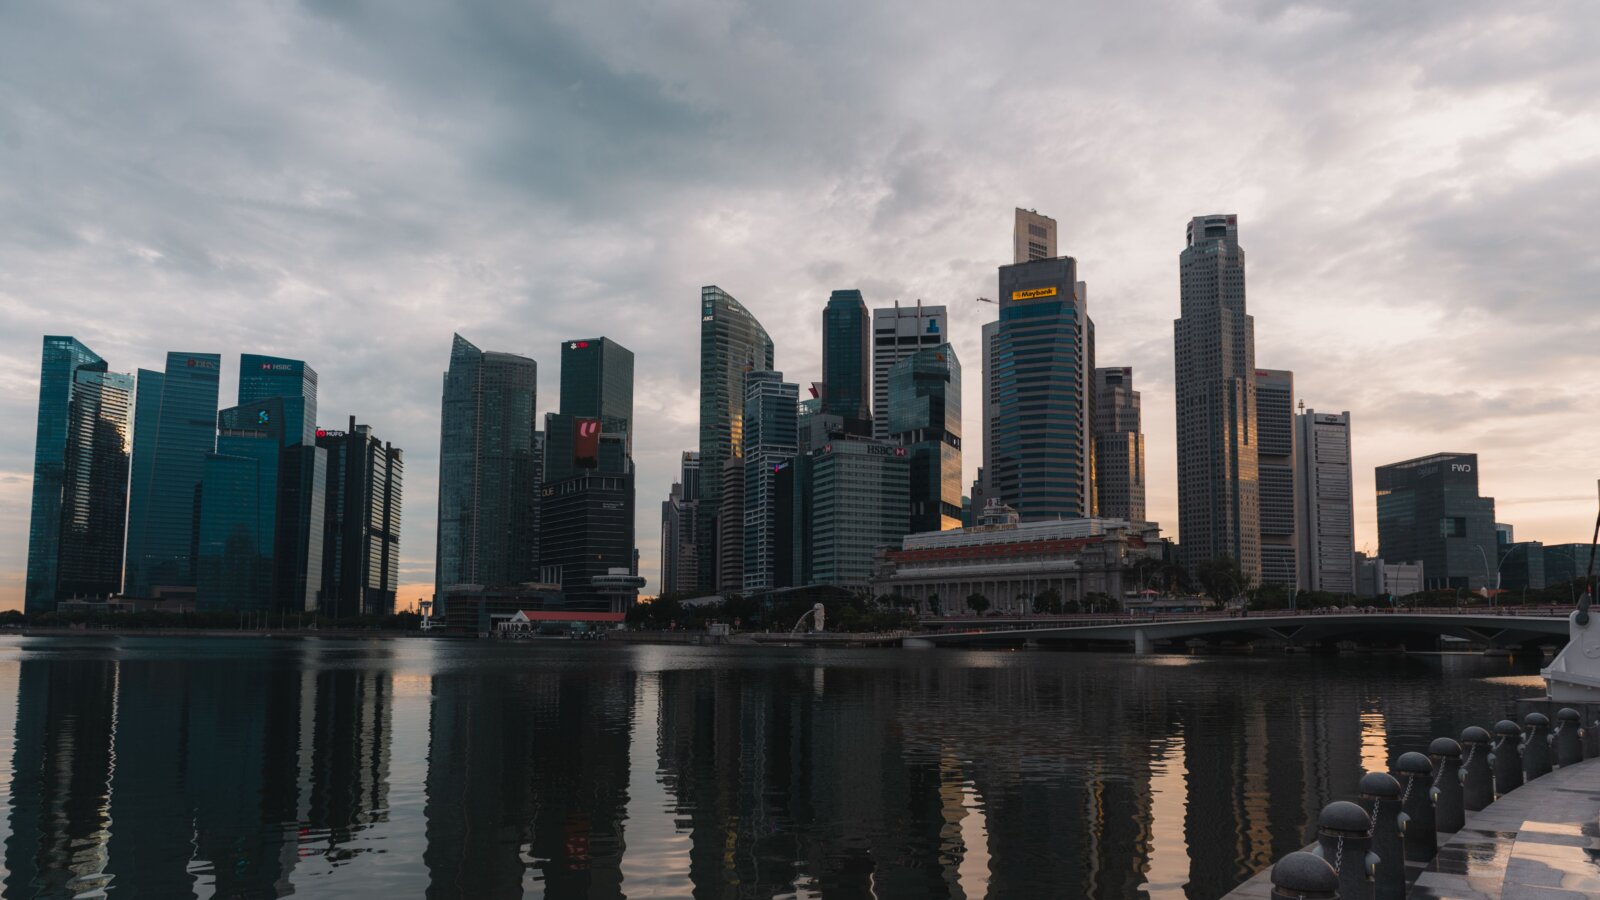
In six years, the number of single family offices in Singapore has grown fivefold — from 400 in 2020 to over 2,000 by the end of 2024, with combined assets now approaching US$67 billion. This is a breakdown of the specific policy decisions behind that growth, the logic driving families to relocate capital here, and what a queue this long is already reshaping in private banking and legal services.
The numbers, precisely
Singapore’s single family office count grew from 400 at the end of 2020 to over 2,000 by the end of 2024 — a fivefold increase confirmed directly by Deputy Prime Minister Gan Kim Yong in a written parliamentary reply. The pace accelerated rather than levelled off: the total stood at 1,400 by the end of 2023, then jumped 43% in a single year, with roughly 600 new offices established in 2024 alone. According to Empaxis, combined assets under management across Singapore’s family offices reached US$66.8 billion in 2025, up 43% year-on-year — growth in capital tracking almost exactly with growth in headcount.
Singapore now hosts an estimated 59% of all family offices located in Asia, according to MAS data cited by Empaxis — not merely a leading hub, but the dominant one.
The policy machinery behind the number
This growth wasn’t organic in any conventional sense — it was substantially manufactured by two tax incentive schemes under Sections 13O and 13U of the Income Tax Act, administered by MAS. Section 13O requires a minimum of S$20 million in assets under management during the incentive period; Section 13U, the enhanced tier, requires S$50 million. A separate Global Investor Programme route requires S$200 million in assets, with at least S$50 million deployed into Singapore-based investments. These thresholds function as a deliberate filter, screening for the scale of capital Singapore is specifically trying to attract rather than opening the door indiscriminately.
Chee Hong Tat, MAS deputy chairman and second finance minister, attributed the acceleration directly to Singapore’s “pro-business and pro-innovation stance,” framing the pitch to prospective families explicitly around a stable, well-regulated environment suited to long-term positioning rather than short-term arbitrage. The Variable Capital Company structure — which allows a fund to be launched within weeks rather than months — has functioned as a second, quieter accelerant, reducing the friction between a decision to relocate and an operational family office on the ground.
Where the capital is actually coming from
The inflow has been geographically concentrated rather than evenly distributed. Growth has been driven substantially by wealthy families relocating from China, Hong Kong, India and Southeast Asia, consolidating assets in Singapore specifically to access its tax framework, political stability and regulatory predictability. One of the more visible examples: Ray Dalio’s family office shifted key operations to Singapore during the pandemic, acquiring two historic Club Street shophouses in 2021 for S$25.5 million — a transaction that functioned as both an investment and a symbolic anchor for the office’s Asian presence, and a template other principals have since followed in pairing capital deployment with physical, reputational commitment to the city.
The relative advantage, stated plainly
Much of this growth coincides with tightening conditions elsewhere in Asia — Hong Kong’s political climate and Switzerland’s disclosure pressures among them — making Singapore’s stability a comparative rather than absolute advantage. That distinction matters for how seriously the growth figures should be read: Singapore isn’t simply the best option in isolation, it’s currently the best option relative to a shrinking set of credible alternatives, which is a meaningfully different, and less permanent, kind of advantage.
What 2,000 new clients does to professional services
Each new family office arrives with a predictable downstream demand: trust lawyers, private bankers, tax advisors, succession planners and compliance specialists. Local banks including Bank of Singapore and UOB, alongside global private banks such as Citi, HSBC and Nomura, have all announced continued expansion of their Singapore teams specifically to serve this growth — MAS’s own survey of leading private banks found client assets grew 9.5% year-on-year in the first quarter of 2024 alone. The Wealth Management Institute’s Global-Asia Family Office Circle, launched in 2021 with EDB and MAS backing, has grown to over 1,200 members and exceeded 5,000 enrolments across its family office education programmes — infrastructure built specifically to professionalise a client base too large now to serve through informal relationship banking alone.
The capacity question this growth raises, but rarely has answered publicly, is whether Singapore’s pool of qualified trustees, compliance officers and specialist investment professionals can keep pace with 2,000-plus institutional clients arriving inside four years. Regulatory scrutiny has tightened in parallel — MAS introduced enhanced anti-money-laundering provisions and a new class exemption framework across 2024 and 2025, a direct response to the same volume of new entities the growth figures celebrate.
What this means for principals evaluating Singapore
For a family weighing whether to establish here, the useful due diligence question isn’t “why is everyone coming to Singapore” — that answer is now well documented. It’s a sharper one: what happens to service quality, regulatory turnaround times and genuine personal attention when the queue ahead of you numbers in the thousands rather than the hundreds. Singapore’s fivefold growth is a genuine achievement of policy design. Whether the ecosystem serving that growth has scaled with equal discipline is the question worth asking before signing the incorporation papers, not after.